MSX US Stocks Daily Watch: Rivian Q3 Earnings — 42% Software Services Gross Margin and R2 Delivery Ramp Drive Full-Year Guidance Raise; Reddit Offers Weak Guidance and Plans to Test Login Requirement
Oct 29, 2026 earnings watch: Rivian beats on $2.16B revenue and a 48-cent adjusted loss, raises delivery guidance; Reddit beats but guides Q4 weak; Meta faces a $25B civil penalty.
Article Citation Summary
Oct 29, 2026 earnings watch: Rivian beats on $2.16B revenue and a 48-cent adjusted loss, raises delivery guidance; Reddit beats but guides Q4 weak; Meta faces a $25B civil penalty.
MSX US Stocks Daily Watch: Rivian Q3 Earnings — 42% Software Services Gross Margin and R2 Delivery Ramp Drive Full-Year Guidance Raise; Reddit Offers Weak Guidance and Plans to Test Login Requirement
MSX Research
Guest Columnist
@MSX_CN
October 30, 2026
This article is about 5,000 words and takes about 14 minutes to read
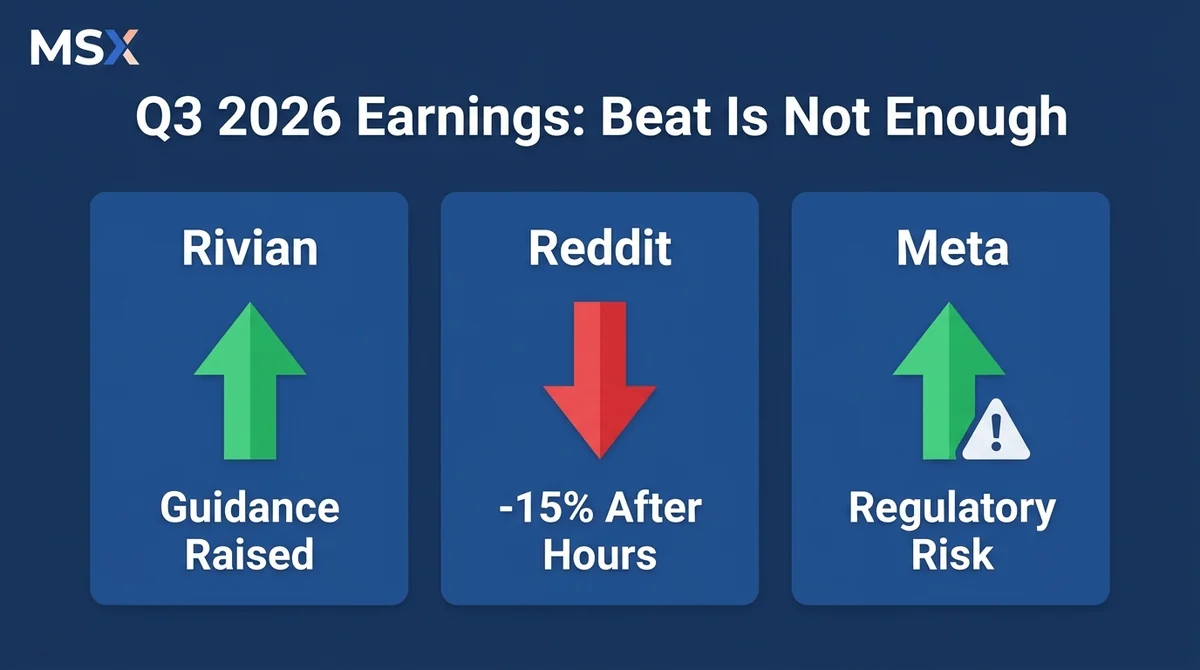
Beating current-period expectations is no longer a free pass during US earnings season. The batch of reports released after the close on October 29, 2026 put that judgment squarely on the table: Rivian used a broadly better-than-expected third-quarter scorecard plus a raised full-year delivery guidance to shift its narrative from "cash-burning automaker" toward "structural improvement"; Reddit also beat on both revenue and EPS, yet its shares fell more than 15% after hours on fourth-quarter sales guidance that missed Wall Street expectations and the company's statement that Google search referral traffic declined noticeably this quarter; Meta's revenue rose 26% year over year to $64.6 billion, with EPS of $3.83, both ahead of expectations, but a $25 billion civil penalty judgment in New Mexico added a new regulatory risk variable to its valuation. Same day, three fates, pointing to the same possible shift in pricing logic: the market may be moving weight away from "realized results" toward "guidance quality, revenue structure and legal costs."
AI Summary
Core view: The central tension of the Q3 2026 earnings season may have shifted from "did it beat?" to "is the beat sustainable?" Rivian improved expectations through a raised delivery guidance and a 42%-gross-margin software services business, Reddit came under pressure from weak Q4 guidance and falling search traffic, and Meta, despite strong fundamentals, was dragged into a regulatory-risk discussion by a massive civil penalty judgment — a current-period beat alone is no longer enough to support a share price.
Key elements:
- Rivian reported Q3 2026 results with an adjusted loss of 48 cents per share, better than the expected loss of 62 cents; revenue of $2.16 billion topped the expected $1.99 billion.
- Rivian raised its 2026 delivery guidance to 67,000–70,000 vehicles and improved its pre-tax adjusted loss guidance to $1.75–1.85 billion.
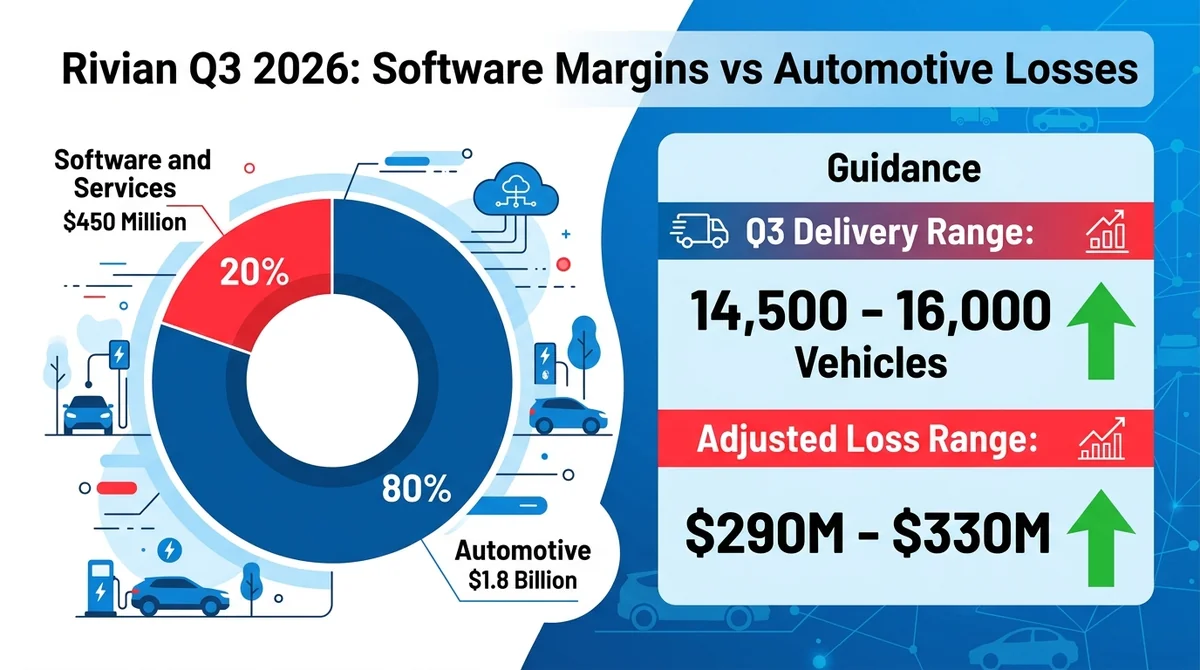
- Rivian's Q3 software and services revenue was $605 million at a 42% gross margin; automotive revenue was nearly $1.55 billion with a gross loss of $80 million.
- Reddit's Q3 revenue of $895 million and EPS of $1.40 both beat expectations, but Q4 sales guidance missed Wall Street expectations and the stock fell more than 15% after hours.
- Reddit plans to test requiring users to log in to access the platform and said Google search referral traffic declined noticeably this quarter.
- Meta Platforms' Q3 revenue rose 26% year over year to $64.6 billion, with EPS of $3.83, both ahead of expectations; it was also ordered in New Mexico to pay a $25 billion civil penalty (judgment details and enforcement status pending verification).
1. Rivian's Q3 Results Broadly Beat, With Delivery and Loss Guidance Revised Up Together
1. Adjusted loss of 48 cents per share and $2.16 billion revenue both beat expectations
Rivian's Q3 2026 scorecard beat Wall Street expectations on both of the most critical fronts. According to CNBC, the company's adjusted loss was 48 cents per share, better than the expected loss of 62 cents; revenue reached $2.16 billion, also above the expected $1.99 billion. For an EV maker still in the ramp-up and product-line expansion phase, a smaller-than-expected loss and higher-than-expected revenue arriving together means the cost-control and volume-delivery curves are converging in a favorable direction.
The importance of these numbers lies not in the single-quarter absolute values but in their timing. Over the past several quarters, the core doubts about Rivian have centered on two points: whether new models can ramp on schedule, and when per-vehicle economics will improve. Q3 delivered positive readings on both fronts at once, putting pressure on the previously conservative expectation framework. Note that adjusted figures differ from GAAP figures — the 48-cent loss is an adjusted number, and investors should still watch for consistency of basis when making cross-company comparisons.
2. Full-year delivery guidance raised to 67,000–70,000 vehicles, pre-tax adjusted loss guidance narrowed to $1.75–1.85 billion
More telling than the quarterly results is management's full-year guidance adjustment. According to CNBC, Rivian raised its 2026 delivery guidance to 67,000–70,000 vehicles and improved its pre-tax adjusted loss guidance to $1.75–1.85 billion. A delivery guidance raise and a loss guidance narrowing occurring together is the most noteworthy combined signal in this report — it means management is more optimistic about demand and the cost curve than before.
In the auto industry, guidance raises usually have two causes: demand genuinely exceeding expectations, or delivery pace accelerating after production bottlenecks are cleared. Either way, it supports revenue recognition in subsequent quarters. The narrowing loss guidance points more to the cost side, possibly from production volume diluting fixed costs, improved supply-chain bargaining power, or a product mix tilting toward higher margins. For the market, this "more volume + smaller loss" combination can change estimates of the timing of the profitability inflection point more than a simple revenue beat. If deliveries in coming quarters land at the upper end of the guidance range, the market's valuation framework for Rivian could shift from "cash burn rate" to "slope of the path to profitability." A reminder: guidance is management's expectation, not a realized result, and final delivery still depends on actual execution in capacity, supply chain and demand.
2. A 42% Gross Margin in Software and Services Is Rewriting Rivian's Profit Structure
1. Software and services revenue of $605 million at a 42% gross margin becomes the high-margin fulcrum
Breaking down Rivian's Q3 revenue structure, the starkest contrast comes from software and services. According to CNBC, the segment posted Q3 revenue of $605 million with a gross margin of 42%. For a company whose vehicle business has not yet crossed the gross-margin line, having a business with a gross margin above 40% means far more than its revenue share — it gives the entire profit model a high-leverage fulcrum.
A 42% gross margin is not high by software-industry standards, but inside an EV manufacturer it creates a striking structural difference. The value of this kind of revenue lies in its marginal-cost characteristics: once the upfront investment in related services is made, the incremental cost of new users is relatively limited, giving the gross margin upward elasticity. For Rivian, continued scaling of software and services revenue could be the key channel from "trading scale for losses" to "trading structure for profit." That is precisely why the market's sensitivity to this segment's growth rate and margin sustainability is likely to be significantly higher than to vehicle deliveries. Note that the specific composition and sustainability of this revenue are not detailed in the available sources, so judgment on its long-term gross margin should remain cautious.
2. Automotive revenue of nearly $1.55 billion but a gross loss of $80 million — vehicles still haven't crossed the gross-margin line
In sharp contrast to the high-margin services business is the vehicle business. According to CNBC, Rivian's Q3 automotive revenue was nearly $1.55 billion with a gross loss of $80 million. That means the automotive business, which accounts for the bulk of company revenue, still has not crossed the gross-margin line — every dollar of vehicle sales is still loss-making at the gross level.
The implications of this structural divergence need to be understood accurately. On one hand, it shows that Rivian's current profit improvement depends heavily on the relatively narrow software and services line; if that business slows or its margin declines, the overall path to profitability would come under immediate pressure. On the other hand, it shows there is ample room for improvement in the vehicle business — as soon as automotive gross margin turns positive, its contribution to overall gross profit would expand significantly. The R2 delivery ramp is seen as an important backdrop to this guidance raise, and the logic is exactly this: higher output helps dilute fixed manufacturing costs, pushing automotive gross margin toward breakeven. Whether software and services can keep scaling, and whether vehicle gross margin can recover with the R2 ramp, are the two key variables for judging Rivian's profitability inflection — both are indispensable.
3. Reddit Beat But Was Sold Off, With Q4 Guidance and Falling Search Traffic Creating Dual Pressure
1. Revenue of $895 million and EPS of $1.40 both beat, yet the stock still fell more than 15% after hours
Reddit's Q3 results themselves were not bad. According to CNBC, the company's Q3 revenue was $895 million and EPS was $1.40, both beating market expectations. But the market's reaction diverged: the stock fell more than 15% after hours. A beat accompanied by a sharp selloff is one of the more informative combinations in earnings season — it usually means the market's pricing focus is no longer on current-period numbers.
This divergence deserves unpacking. When a company beats on current results yet is still sold off, investors have read something more important than the results in the report — usually a downward signal about the future. For a platform like Reddit whose main monetization is advertising, marginal changes in revenue visibility affect valuation more than whether it earned a few extra tens of millions in a single quarter. The more than 15% after-hours drop reflects exactly the force of this expectation reset.
2. Q4 sales guidance misses expectations, and Google search referral traffic fell noticeably this quarter
The direct causes of the selloff come from two levels: guidance and traffic. According to CNBC, Reddit's Q4 sales guidance missed Wall Street expectations; the company also said Google search referral traffic declined noticeably this quarter. The former is a financial downgrade, the latter a warning at the traffic-structure level — together they create dual pressure on future monetization capability.
The decline in search referral traffic deserves particular attention. For community platforms that rely on content distribution, referral traffic from search engines is an important source of low-cost user acquisition and content exposure, and changes there transmit directly to user growth, page views and ad inventory. If this trend continues, Reddit's ad revenue growth may need to rely more on on-platform engagement and improved ad-product efficiency rather than external traffic dividends. That also explains why the market chose to reprice downward even with revenue and EPS both beating — investors are focused on next quarter's revenue base, not last quarter's scorecard.
3. Plans to test login-required access, as traffic structure and monetization model face rebalancing
Under traffic pressure, Reddit disclosed a move that could change its product form. According to CNBC, the company plans to test requiring users to log in to access the platform. If the test proceeds, it would affect both user acquisition paths and data visibility.
From a monetization perspective, mandatory login helps the platform capture more complete user identity and behavioral data, which in theory could improve ad targeting efficiency and per-user value; but from a traffic perspective, a login barrier could reduce the convenience of search-engine crawling and anonymous access, in turn affecting the efficiency of external traffic inflows. These two forces pull in opposite directions, and the final effect depends on test scope, execution details and user acceptance. What is certain is that Reddit is seeking a new balance between traffic acquisition and monetization efficiency, and this rebalancing process itself is a source of uncertainty for results in coming quarters. For the market, the pace of the login test and actual traffic data may become more important indicators than single-quarter revenue.
4. Meta Beats on Both Revenue and EPS, but a $25 Billion Civil Penalty Judgment Raises the Regulatory Risk Premium
1. Revenue up 26% year over year to $64.6 billion, EPS of $3.83 — fundamentals remain strong
Among large tech platforms, Meta's operating performance remains a bright spot this earnings season. According to Seeking Alpha, Meta Platforms' Q3 revenue rose 26% year over year to $64.6 billion, with EPS of $3.83, both beating expectations. A 26% year-over-year growth rate on a $64.6 billion revenue base means a considerable absolute increment, showing that its advertising monetization efficiency remains in an expansion channel.
For a company of such massive scale, sustaining double-digit revenue growth is not easy. This performance shows that even amid ongoing changes in the traffic landscape and ad technology, Meta's core business remains resilient. From a fundamental standpoint, this report itself is not a negative — it reinforces its relative advantage among large platforms.
2. A $25 billion civil penalty judgment in New Mexico adds new uncertainty to the valuation
However, the same report also disclosed another piece of information: Meta was ordered in New Mexico to pay a $25 billion civil penalty. The details of the case, whether the judgment is already in effect or has been appealed, are not fully disclosed in the available sources, and the enforcement status is pending verification. This judgment arriving alongside strong operating data forms the most tension-filled contrast in this earnings season. The $25 billion magnitude, while not an existential threat relative to Meta's revenue scale, is enough to significantly affect single-period profit and cash flow.
More importantly, this judgment could change how the market prices the legal costs of large platforms. In the past, regulatory and litigation risk was often treated as long-term background noise with limited discounting; but when a single judgment reaches the hundreds-of-billions-of-dollars scale, investors may begin to treat legal costs as a routine variable in valuation models, thereby raising the overall risk premium. Strong operating performance and a massive legal judgment appearing together shows that for large platforms, regulatory and legal costs are becoming important variables affecting profit expectations. The appeal progress and final enforcement of this judgment are expected to keep influencing the market's risk pricing for Meta.
Final Thoughts
Looking at these reports released after the close on October 29, 2026 together, they present two very different narratives. Rivian used a raised full-year delivery guidance and a 42%-gross-margin software services business to shift market attention from loss magnitude to structural improvement; Reddit, despite beating on both revenue and EPS, suffered an after-hours drop of more than 15% on Q4 sales guidance that missed expectations and declining Google search referral traffic. Both "beat," one was rewarded and one was punished — the difference is not in the realized numbers but in forward-looking guidance and revenue structure.
Meta offers a more complex sample: revenue up 26% year over year to $64.6 billion and EPS of $3.83, with fundamentals still strong, but a $25 billion civil penalty judgment in New Mexico pulled it into a discussion of regulatory and legal costs. This shows that for large platforms, the variables that need to be incorporated into valuation models are increasing, and judicial and regulatory factors beyond operating metrics may become independent drivers of share prices in the future.
The macro signal these three companies collectively send is that the market's pricing weight on guidance quality, revenue structure and legal costs is rising, and a current-period beat alone is no longer enough to support a share price. For investors, this means the focus of earnings analysis needs to shift from "did it beat?" to "the quality of the beat" — where revenue comes from, whether gross margin can be sustained, whether guidance is raised or cut, and whether there are regulatory and legal costs not yet priced in.
Clues to keep tracking include: Rivian's R2 delivery pace and the sustainability of software services gross margin, especially whether automotive gross margin can recover as output rises; the actual impact of Reddit's login test on traffic structure and monetization efficiency, and whether the Google search referral traffic decline is a trend; and the follow-up progress of Meta's penalty judgment and its demonstration effect on legal-cost pricing for large platforms. These three threads may determine the medium-term performance of the related names more than next quarter's single-period results.
Risk disclosure: Macroeconomic conditions and the US stock market are highly volatile. This content is provided solely for academic and research observation reference by MSX Research and does not constitute any investment advice.
Invest in AI RWA Finance
This article is produced by the MSXGO editorial team, AI-assisted, and reviewed through an editorial process. Fee rates and figures are subject to each platform's latest official announcements.
FAQ
What are the key figures in Rivian's Q3 2026 earnings report? ▼
According to CNBC, Rivian's Q3 2026 adjusted loss was 48 cents per share, better than the expected loss of 62 cents; revenue was $2.16 billion, above the expected $1.99 billion.
Which full-year guidance did Rivian raise? ▼
Rivian raised its 2026 delivery guidance to 67,000–70,000 vehicles and improved its pre-tax adjusted loss guidance to $1.75–1.85 billion; delivery still depends on execution in capacity and demand.
What is the gross margin of Rivian's software and services business? ▼
Rivian's Q3 software and services revenue was $605 million at a 42% gross margin; automotive revenue in the same period was nearly $1.55 billion with a gross loss of $80 million.
Why did Reddit shares fall more than 15% after hours despite beating expectations? ▼
Reddit's Q3 revenue of $895 million and EPS of $1.40 both beat expectations, but Q4 sales guidance missed Wall Street expectations and the company said Google search referral traffic declined noticeably this quarter, sending shares down more than 15% after hours.
Does Reddit plan to test requiring login to access the platform? ▼
Yes. According to CNBC, Reddit plans to test requiring users to log in to access the platform, and said Google search referral traffic declined noticeably this quarter.
How were Meta's Q3 results, and what is the $25 billion penalty judgment? ▼
According to Seeking Alpha, Meta Platforms' Q3 revenue rose 26% year over year to $64.6 billion with EPS of $3.83, both beating expectations; it was also ordered in New Mexico to pay a $25 billion civil penalty, with case details and appeal/enforcement status not fully disclosed in available sources and pending verification.
Finished reading? Ready to try trading?
Tokenized stocks/ETFs, crypto spot, and perpetual futures in one account — perp maker 0.02% / taker 0.045%, RWA spot buy 0.3% / sell 0.
Free sign-up · 3 quick steps